Published in Market Analysis
The Netherlands Is Shipping 20% Fewer Pigs to Slaughter, and Europe's Pig Price Has Not Noticed
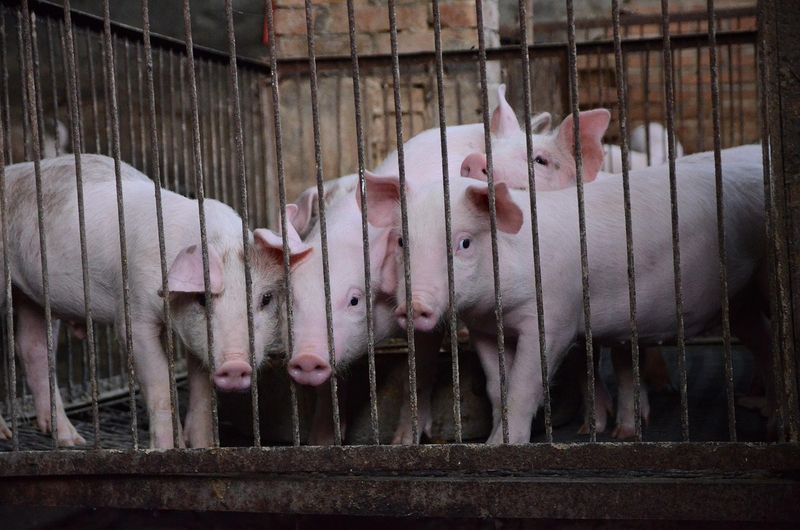
Dutch exports of pigs for slaughter fell 20% in January to September while the EU pig price sits about 14% below last year, and our view is that the Dutch shrink is showing up in live pig flows and slaughter capacity long before it shows up in price.
Martina Osmak
Director of Marketing
MeatBorsa's take
This section is our reading of the news, not reported fact. The confirmed figures follow below.
The Dutch pig sector is getting smaller, and the first place you can see it is not the price. It is the flow of live pigs across borders and the number of slaughter lines in use. In the first nine months of 2026, the Netherlands sent about one in five fewer pigs abroad for slaughter, and Vion is moving the volumes of its Apeldoorn plant to other Dutch sites. Meanwhile the EU pig price is about 14% below last year and German prices kept falling through October.
Our view is that these two facts do not contradict each other. The Netherlands produces about 6% of EU pork, so a shrinking Dutch herd is a regional supply story, while the price is being set by a much bigger problem: plenty of pigs across Europe and weaker export demand. A smaller Dutch herd removes pigs from the system slowly. Weak demand pushes on the price every week.
What we think this means for the next few months is a change in shape more than in price. German slaughterhouses in the border regions have fewer Dutch pigs to fill their lines, Dutch plants are consolidating to keep their own lines full, and the pigs that remain are more likely to be slaughtered and sold as pork inside the Netherlands rather than shipped live. For buyers of pork, the visible change could be in which plant and which country a product comes from, not in what it costs.
What we assume, and why we could be wrong
- We assume the Dutch reduction is too small to move the EU price on its own. If other large producers cut pig numbers at the same time, the combined effect could reach the price sooner than we expect.
- We assume weak export demand stays the main price driver. If demand outside Europe picks up, a smaller Dutch supply base would show up in tighter availability faster.
- We assume slaughter capacity keeps following the herd down, with a delay. If plants cut lines faster than pig numbers fall, competition for the remaining pigs could support Dutch prices even while the EU average stays weak.
- We assume part of the export drop is pigs being slaughtered at home rather than pigs disappearing. The data on live exports alone cannot separate the two, so some of the fall may be relocation, not reduction.
What the numbers actually say
According to pig333, using data from the Netherlands Enterprise Agency (RVO) published on 6 November, the Netherlands exported 274,526 pigs for slaughter in weeks 1 to 39 of 2026. That is 20.2% fewer than the 344,100 shipped in the same period of 2025. Ten years ago the same period saw about 2.45 million pigs leave the country for slaughter.
Germany remains by far the main destination, taking 229,509 pigs, or 83.6% of the total, which is 19.3% less than last year. Shipments to Spain dropped 66%, from 41,958 to 14,252 pigs. Belgium moved the other way, rising from 2,366 to 14,931 pigs, and Italy took 15,514 pigs, up 11.4%.
The USDA Foreign Agricultural Service office in The Hague, in a report dated 2 November, says Dutch slaughterhouses now process about 50,000 fewer pigs per week than five years ago, when the figure was 331,500 per week. It notes that Vion links the closure of its Apeldoorn slaughterhouse to the smaller Dutch herd, with production moving to other Vion sites. The report also records that the Dutch government's farm buyout programmes, known as LBV and LBV-plus, have a combined budget of nearly €3 billion, and that 573 of the 1,576 farmers who applied are pig farmers. It forecasts a further fall in Dutch pig slaughter in 2027.
The price side tells a different story:
- EU average pig price: €153.3 per 100 kg for class S carcasses in week 44, down 2.0% on the week and 13.6% on the year, according to the European Commission's weekly price report updated on 4 November.
- Dutch price, September average: €117.19 per 100 kg for class S, 24.9% below a year earlier, in the same Commission report.
- German slaughter pig price (VEZG): started October at €1.45 per kg and ended it at €1.32, a fall of 13 cents in one month, as reported by pig333 on 2 November.
- Dutch farm margins: negative for fattening farms in the first seven months of 2026 and only slightly positive in August, with carcass prices at a four-year low, according to the USDA report.
The same German market report also says Vion plans to stop slaughtering at Apeldoorn by the end of the year, and that piglet prices in Germany fell from €30 to €25 per head during October.
What we are watching next
We are watching whether the RVO export figures for October and November continue to fall at the same pace, and whether Germany's share of Dutch live pig exports holds above 80%. A sharp drop in shipments to one destination would tell us more about plant capacity on the other side of the border than about Dutch supply.
We are also watching the weekly EU price for the first sign that the gap between the Dutch and German prices narrows as Dutch slaughter capacity tightens. Buyers who source Dutch or German pork may want to ask their suppliers whether the plant packing their product has changed this year, and whether any volumes are moving between sites.
Sources
Dutch exports of pigs for slaughter fall by 20% through September 2026 - pig333
Outlook of the Dutch Swine Sector (NL2026-0021) - USDA Foreign Agricultural Service
German pig market in October: Price pressure shows no sign of easing - pig333